Summary


Japanese value stocks are still trading at an attractive discount to Japanese growth stocks.

Japan’s broad Topix index reached their highest in 33 years last week and is up 10.6% in USD terms this year1. The market’s ascent is sweet vindication for investors who have kept the faith. Eastspring’s Japan equity team has long pointed to the market’s cheap valuations, potential for corporate reforms and improving profit margins as reasons to be positive. These factors may finally be gaining traction with investors.

At 1.3x price to book valuation2 , Japan is more attractively priced than the US, European and Asia ex Japan markets. This is despite Japan’s cash earnings, as measured by the cash earnings yield, being superior. Profit margins are also trending higher on the back of efficiency gains. Improving corporate governance is another key structural change for the Japanese market. There has been a rising representation of independent directors on company boards over the years, including a number of activist fund managers on the boards of prominent companies. 77% of the companies in the Topix have independent directors that make up at least one third of their boards 3. A greater focus on shareholder value has been accompanies by a rise in dividends and share buybacks. More recently, new rules for the Tokyo Stock Exchange require companies that persistently trade below their book value to disclose plans to remedy the situation. This may encourage companies to exert greater effort to increase their corporate value.

On the macro front, pent up domestic demand from Japan’s re-opening in the first half of the year, the positive spill over from China’s re-opening and the removal of supply constraints will help support the Japanese economy in 2023. While weak exports would weigh on the Japanese economy going forward, the stronger than expected wage hikes from the recent spring wage negotiations may help sustain consumer spending. Wage hikes can make consumers more tolerant of higher prices, potentially leaving room for companies to raise prices. Consumer price inflation has been above 2%, the Bank of Japan’s target since April 2022. If sustained, this could spell the end to Japan’s decades of deflation, potentially positioning private demand as an important driver of economic growth.

Eastspring’s Japan equity team continues to be disciplined in seeking mispriced companies and focusing on companies’ sustainable cashflows. While the market has rallied, the good news is that Japanese value stocks are still trading at an attractive discount to Japanese growth stocks. While there could be some bumps along the way, further potential upside awaits the patient investor.
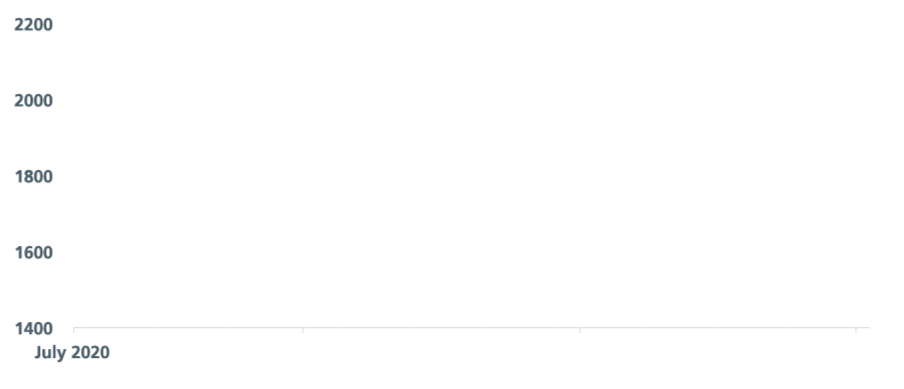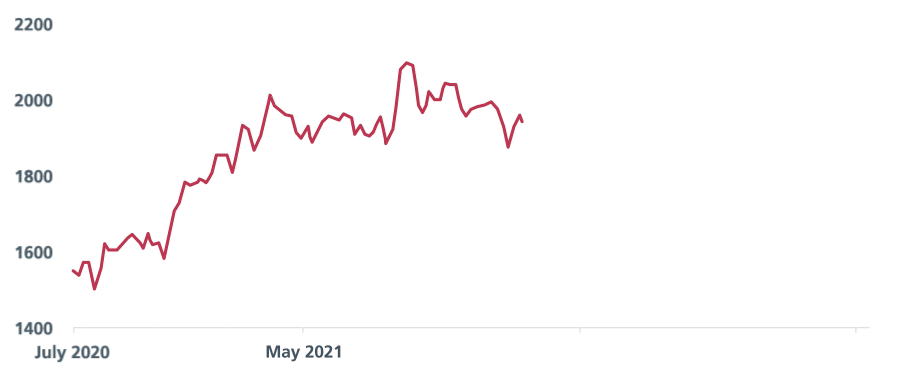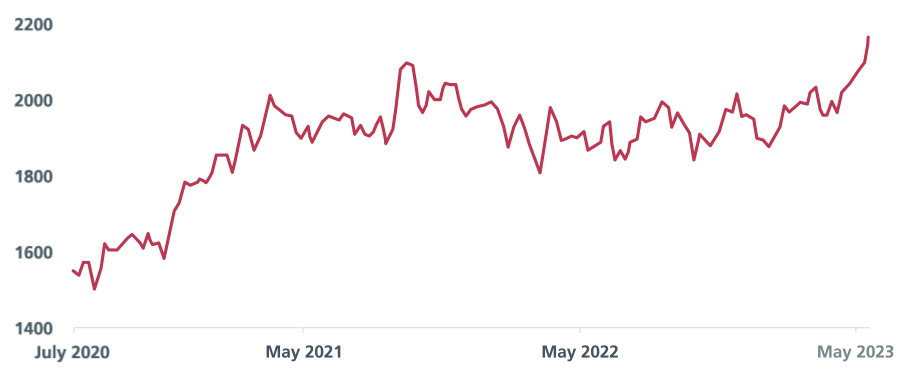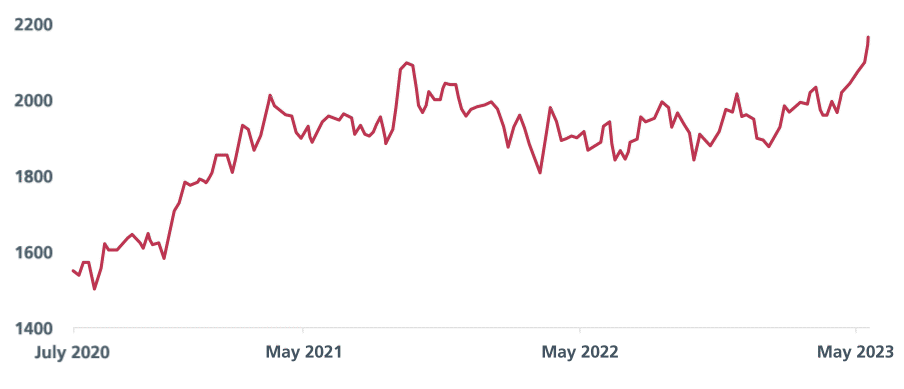
Image of Japan’s broad Topix index growth

Source: Bloomberg. As of 22 May 2023.


Interesting reads

Know more
What’s next after the tech sell-off?

in insights

Equity

What’s next after the tech sell-off?

06 Nov

The tech-led sell-off reflects concerns over AI financing costs and tighter data ...

Four key conclusions from the US midterm election

in insights

Equity

Four key conclusions from the US midterm election

04 Nov

The US mid-term elections delivered a broad Democratic victory, but the implications ...

The AI reset - Fundamentals take centre stage

in insights

Equity

The AI reset - Fundamentals take centre stage

03 Nov

The recent sell-off in global technology stocks reflects greater scrutiny, not ...

CIO Views: US elections and US payrolls – what to watch for

in insights

CIO Views: US elections and US payrolls – what to watch for

02 Nov | Ray Farris , Vis Nayar

Although much of the recent financial market anxiety about US AI capex spending has ...

From AI adoption to monetisation

in insights

Equity

From AI adoption to monetisation

28 Oct | Jack Hsu , Louis Cheng

AI adoption is accelerating, but adoption alone does not create value. Find out where ...

CIO Views: Central banks on hold will allow a focus on Tech results

in insights

CIO Views: Central banks on hold will allow a focus on Tech results

26 Oct | Ray Farris , Vis Nayar

A slew of earnings announcements this week from IT hardware producers across Asia and ...

4Q 2026 Market Outlook: Resilience meets rising risks

in insights

Multi asset

4Q 2026 Market Outlook: Resilience meets rising risks

23 Oct

Asia’s growth may moderate but remain resilient as energy prices lift inflation and ...

Japan Equities: Is the investment case sustainable?

in insights

Equity

Japan Equities: Is the investment case sustainable?

22 Oct | Ivailo Dikov , James Ying

Stronger fundamentals underpin Japan’s investment case. Improving profitability ...

Indonesia’s MSCI review –What it means for investors

in insights

Equity

Indonesia’s MSCI review –What it means for investors

19 Oct

Indonesia’s equity market is facing renewed challenges after MSCI announced on ...

What tech sell offs mean for investors Oct 2026

in insights

Equity

What tech sell offs mean for investors Oct 2026

19 Oct

Recent tech weakness reflects a reset in sentiment, not fundamentals. Underlying AI ...

Sources:
1 Bloomberg. As of 22 May 2023.
2 Eastspring Investments, IBES MSCI Indices, Refinitiv Datastream, as at 31 March 2023. Indices used: MSCI Japan Index, MSCI Europe Index, MSCI AC Asia Pacific ex-Japan, MSCI EM Latin America Index, MSCI AC World Index, MSCI USA Index.
3 Nomura and Bloomberg, as at 31 March 2023. Universe is TOPIX. Based on company's data and Bloomberg.

This document is produced by Eastspring Investments (Singapore) Limited and issued in:

Singapore by Eastspring Investments (Singapore) Limited (UEN: 199407631H)

Australia (for wholesale clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore, is exempt from the requirement to hold an Australian financial services licence and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Australian laws

Hong Kong by Eastspring Investments (Hong Kong) Limited and has not been reviewed by the Securities and Futures Commission of Hong Kong.

Indonesia by PT Eastspring Investments Indonesia, an investment manager that is licensed, registered and supervised by the Indonesia Financial Services Authority (OJK).

Malaysia by Eastspring Investments Berhad (200001028634/ 531241-U) and Eastspring Al-Wara’ Investments Berhad (200901017585 / 860682-K) and has not been reviewed by Securities Commission of Malaysia.

Thailand by Eastspring Asset Management (Thailand) Co., Ltd.

United States of America (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is registered with the U.S Securities and Exchange Commission as a registered investment adviser.

European Economic Area (for professional clients only) and Switzerland (for qualified investors only) by Eastspring Investments (Luxembourg) S.A., 26, Boulevard Royal, 2449 Luxembourg, Grand-Duchy of Luxembourg, registered with the Registre de Commerce et des Sociétés (Luxembourg), Register No B 173737.

Chile (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Chilean laws.

The afore-mentioned entities are hereinafter collectively referred to as Eastspring Investments.

The views and opinions contained herein are those of the author, and may not necessarily represent views expressed or reflected in other Eastspring Investments’ communications. This document is solely for information purposes and does not have any regard to the specific investment objective, financial situation and/or particular needs of any specific persons who may receive this document. This document is not intended as an offer, a solicitation of offer or a recommendation, to deal in shares of securities or any financial instruments. It may not be published, circulated, reproduced or distributed without the prior written consent of Eastspring Investments. Reliance upon information in this document is at the sole discretion of the reader. Please carefully study the related information and/or consult your own professional adviser before investing.

Investment involves risks. Past performance of and the predictions, projections, or forecasts on the economy, securities markets or the economic trends of the markets are not necessarily indicative of the future or likely performance of Eastspring Investments or any of the funds managed by Eastspring Investments.

Information herein is believed to be reliable at time of publication. Data from third party sources may have been used in the preparation of this material and Eastspring Investments has not independently verified, validated or audited such data. Where lawfully permitted, Eastspring Investments does not warrant its completeness or accuracy and is not responsible for error of facts or opinion nor shall be liable for damages arising out of any person’s reliance upon this information. Any opinion or estimate contained in this document may subject to change without notice.

Eastspring Investments companies (excluding joint venture companies) are ultimately wholly owned/indirect subsidiaries of Prudential plc of the United Kingdom. Eastspring Investments companies (including joint venture companies) and Prudential plc are not affiliated in any manner with Prudential Financial, Inc., a company whose principal place of business is in the United States of America or with the Prudential Assurance Company Limited, a subsidiary of M&G plc (a company incorporated in the United Kingdom).