Summary


Chinese households are flushed with cash. It is estimated that Chinese households have accumulated RMB13tr (USD1.9 tr) in additional deposits as they consumed less (due to the lockdowns), were more risk averse and bought less property over the past three years.

Where will all this money go now that China has re-opened? Our team in China expects consumer spending to rise, especially in services. Dental and aesthetics treatments are likely to surge on the back of pent-up demand. The team expects consumer spending to be an important driver of China’s economic recovery this year. While the Chinese property sector is seeing some green shoots – home sales of China’s top 100 developers rose 15% in February from the same month last year - property purchases are likely to remain moderate.

Our investment team based in Singapore also expects Chinese tourism to rise, benefitting Asia. Chinese travelers reportedly made 155 million trips overseas in 2019, accounting for 20% of the total spend by international tourists. The Civil Aviation Administration of China (CAC) expects total air traffic for 2023 to reach 75% of pre-pandemic levels.

The A-share market may also benefit from the excess deposits. Lessons from the developed and emerging markets on the behaviours of households post re-openings show that some of the excess deposits tend to make their way into the domestic stock markets1. The analysis also shows that retail inflows into the domestic stock markets happen with a lag (after the market has rallied), after consumer confidence has recovered.

We note that Chinese retail inflows into mutual funds have been muted in 2022. If Chinese households behave in a similar fashion to their developed and emerging market counterparts, retail inflows from Chinese investors may pick up in the coming months. This suggests that although the A-share market has rallied 12%2 since November, there could be another leg to the rally.
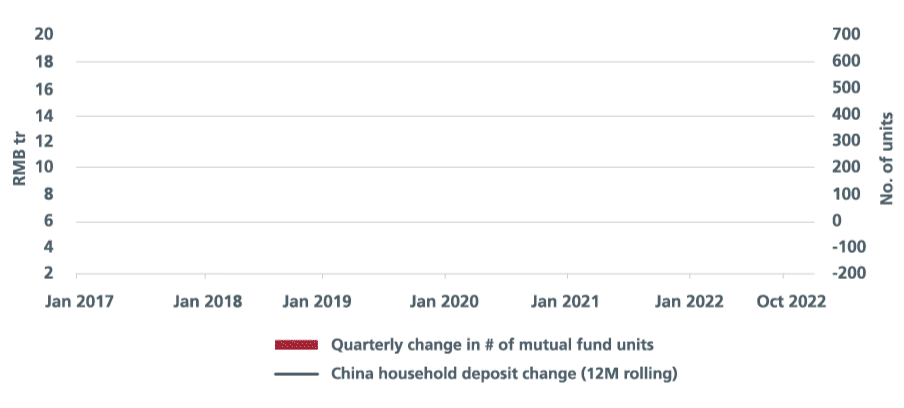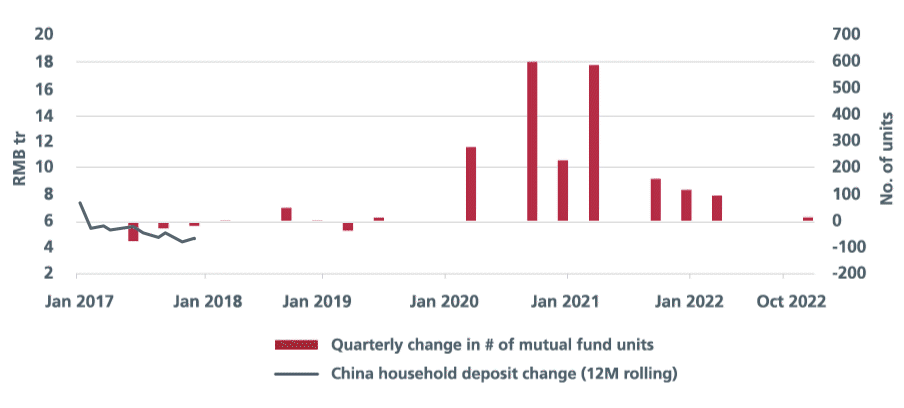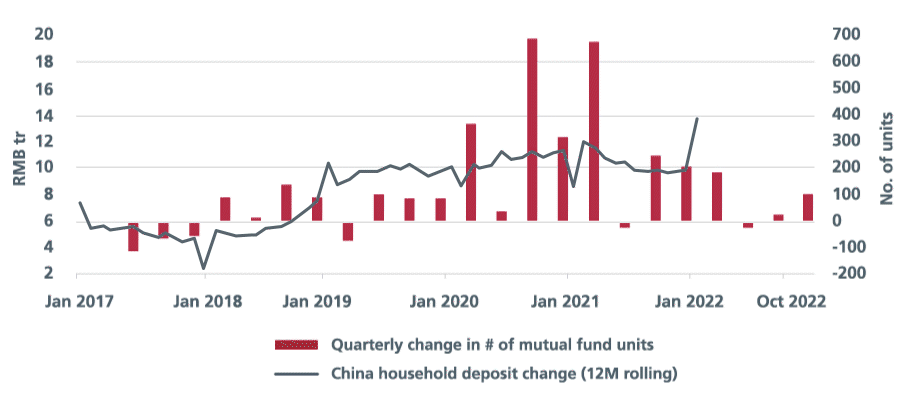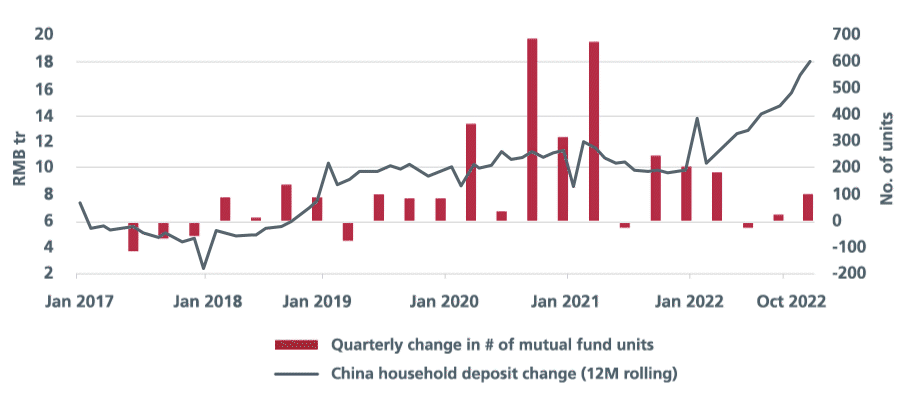
Chinese retail inflows into mutual funds vs Chinese household deposits

Where will all the Chinese deposits go

Source: Wind. CEIC. UBS. Note: Onshore mutual fund issuance is used as a proxy for retail flows. March 2023.


Interesting reads

Know more
CIO Views: Increased need for selective investment

in insights

CIO Views: Increased need for selective investment

28 Sep | Ray Farris , Vis Nayar

Geopolitics continue to challenge markets. The Xi-Trump meeting produced little ...

Asian Fixed Income:  Resilient through the rates shock

in insights

Multi asset

Asian Fixed Income:  Resilient through the rates shock

25 Sep

Asia fixed income has absorbed less of the recent global rates shock, reflecting ...

Is staying under-allocated to Emerging Market Debt the greater risk?

in insights

Fixed income

Is staying under-allocated to Emerging Market Debt the greater risk?

22 Sep | Eric Fang , Gabriel Tay

Emerging Market Debt is broader, higher quality and more investable than many ...

CIO Views: Higher yields raise the bar for equity returns

in insights

CIO Views: Higher yields raise the bar for equity returns

21 Sep | Ray Farris , Vis Nayar

The Fed may still be behind the market despite its hawkish tone. Markets are pricing ...

Asia Fixed Income – A carry and security selection story

in insights

Fixed income

Asia Fixed Income – A carry and security selection story

16 Sep

Carry remains the main return driver with the best opportunities in markets where ...

CIO Views: Oil shock returns as central banks confront rising yields

in insights

CIO Views: Oil shock returns as central banks confront rising yields

14 Sep | Ray Farris , Vis Nayar

Rising oil prices have returned to focus as the rapid re-escalation in the Middle ...

Asia Technology: What matters for investors

in insights

Equity

Asia Technology: What matters for investors

09 Sep | Eric Lin

The AI investment cycle remains well supported, with demand expanding beyond initial ...

Key insights from Eastspring’s 2026 China Investment Summit

in insights

Multi asset

Key insights from Eastspring’s 2026 China Investment Summit

08 Sep

Applications may define the next phase of the AI revolution, broadening the group of ...

CIO Views: How to think about the coming US inflation data

in insights

CIO Views: How to think about the coming US inflation data

07 Sep | Ray Farris , Vis Nayar

US inflation risks may be higher than market expectations: While August core CPI is ...

Navigating EM concentration through an active value approach

in insights

Equity

Navigating EM concentration through an active value approach

03 Sep | Navin Hingorani

· EM’s recent outperformance has renewed investor interest, but passive exposure is ...

Sources:
1UBS. China Equity Strategy. March 2023.
2As of 2 March 2023.

This document is produced by Eastspring Investments (Singapore) Limited and issued in:

Singapore by Eastspring Investments (Singapore) Limited (UEN: 199407631H)

Australia (for wholesale clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore, is exempt from the requirement to hold an Australian financial services licence and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Australian laws

Hong Kong by Eastspring Investments (Hong Kong) Limited and has not been reviewed by the Securities and Futures Commission of Hong Kong.

Indonesia by PT Eastspring Investments Indonesia, an investment manager that is licensed, registered and supervised by the Indonesia Financial Services Authority (OJK).

Malaysia by Eastspring Investments Berhad (200001028634/ 531241-U) and Eastspring Al-Wara’ Investments Berhad (200901017585 / 860682-K) and has not been reviewed by Securities Commission of Malaysia.

Thailand by Eastspring Asset Management (Thailand) Co., Ltd.

United States of America (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is registered with the U.S Securities and Exchange Commission as a registered investment adviser.

European Economic Area (for professional clients only) and Switzerland (for qualified investors only) by Eastspring Investments (Luxembourg) S.A., 26, Boulevard Royal, 2449 Luxembourg, Grand-Duchy of Luxembourg, registered with the Registre de Commerce et des Sociétés (Luxembourg), Register No B 173737.

Chile (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Chilean laws.

The afore-mentioned entities are hereinafter collectively referred to as Eastspring Investments.

The views and opinions contained herein are those of the author, and may not necessarily represent views expressed or reflected in other Eastspring Investments’ communications. This document is solely for information purposes and does not have any regard to the specific investment objective, financial situation and/or particular needs of any specific persons who may receive this document. This document is not intended as an offer, a solicitation of offer or a recommendation, to deal in shares of securities or any financial instruments. It may not be published, circulated, reproduced or distributed without the prior written consent of Eastspring Investments. Reliance upon information in this document is at the sole discretion of the reader. Please carefully study the related information and/or consult your own professional adviser before investing.

Investment involves risks. Past performance of and the predictions, projections, or forecasts on the economy, securities markets or the economic trends of the markets are not necessarily indicative of the future or likely performance of Eastspring Investments or any of the funds managed by Eastspring Investments.

Information herein is believed to be reliable at time of publication. Data from third party sources may have been used in the preparation of this material and Eastspring Investments has not independently verified, validated or audited such data. Where lawfully permitted, Eastspring Investments does not warrant its completeness or accuracy and is not responsible for error of facts or opinion nor shall be liable for damages arising out of any person’s reliance upon this information. Any opinion or estimate contained in this document may subject to change without notice.

Eastspring Investments companies (excluding joint venture companies) are ultimately wholly owned/indirect subsidiaries of Prudential plc of the United Kingdom. Eastspring Investments companies (including joint venture companies) and Prudential plc are not affiliated in any manner with Prudential Financial, Inc., a company whose principal place of business is in the United States of America or with the Prudential Assurance Company Limited, a subsidiary of M&G plc (a company incorporated in the United Kingdom).