

Nov 2026|5 min read


Executive Summary
Indian equities have been challenged by high energy prices, currency volatility and foreign investor outflows. These headwinds are compounded by their relatively limited participation in the AI-driven rally. Yet, our conversations with company management and locals during a two-week road trip through Delhi, Mumbai, Pune and Lucknow revealed an economy that is proving more resilient than many investors appreciate, alongside emerging investment opportunities for those who know where to look.
An underappreciated resilience
India’s domestic demand remains resilient despite higher food and energy prices weighing on household purchasing power, particularly in the rural areas. According to vehicle dealers, customer interest in two-wheelers remain healthy and two-wheeler factories are operating at high utilisation rates. Based on registration data, two-wheeler registrations reached 11.04 mn units for FY27 year to date (April to September 2026), up 20.4% yoy. September’s registrations alone were up 33.1% from the same period last year and higher by 4.4% from August1. Meanwhile, the pipeline for infrastructure projects remained buoyant, and sentiment in rural areas was more constructive than we had expected.
Although India remains vulnerable to external shocks, particularly through imported energy; decades of investments in infrastructure, as well as years of continued formalisation have broadened the economy’s foundations across industries and income groups, making India’s economic growth less dependent on any single engine.
This was especially obvious from our visit to Lucknow, the capital of India’s most populous state. In Lucknow, better roads, stronger connectivity and improved administration over the years have created a more predictable operating environment and instilled greater corporate confidence. Our visits to a modern specialist hospital, education centre and a large upscale shopping mall showed that householders are spending more on healthcare, education and experiences, which is in turn helping to attract more private capital outside India’s tier-one cities.
The other side of rising costs
Investors have been concerned around the rising costs from higher interest rates and minimum wage hikes. The Reserve Bank of India (RBI) raised interest rates by 25 basis points in October to address inflation risks from higher oil prices. However, the RBI’s shift to “calibrated tightening”, suggests a measured rather than aggressive tightening cycle. We believe the gradual move strengthens the RBI’s credibility and could benefit banks through higher rates, while limiting the impact on the broader economy.
We also have a more sanguine view on the recent minimum wage hikes. In April, the northern state of Haryana raised minimum wages by around 35% following worker protests. Since then, more than 10 states have followed, with increases ranging from 10% to 60%. Our trip suggested that wage pressures are extending beyond states that have formally raised minimum wages. For example, a Pune-based auto-parts plant had to match Haryana’s increase to retain workers who might otherwise return to their home states in northern and eastern India. A leading quick-service restaurant operator has similarly raised minimum wages in half of the states where it operates, and likely to do the same in the remaining states.
While higher wages may weigh on corporate margins in the near term, they could support consumption over time. Blue-collar households tend to spend a larger share of additional income, potentially lifting demand for two-wheelers, mobile phones, household appliances and home improvements. Higher incomes may also improve loan servicing and remittances.
The market is currently focused on the immediate margin pressure from higher wages, potentially overlooking the subsequent boost to demand. The transfer of income from companies to employees is at an early stage - we are closely monitoring the transition and where potential investment opportunities may emerge.
3 investment themes from our trip
Against this backdrop, our trip highlighted three investment themes that look beyond near-term cost pressures to the structural shifts in India’s economy.
Auto -ancillaries. Auto-ancillaries or companies that manufacture critical vehicle components such as engines, transmissions, brakes, electrical systems and tires for Original Equipment Manufacturers (OEMs) emerged as the highest conviction theme from our trip. Vehicle demand remains buoyant across most categories, while manufacturers are adding capacity, accelerating electrification and sourcing more components locally. Given that there are relatively few quality suppliers that OEMs trust, selected auto-parts companies benefit from both higher industry volumes and rising content per vehicle. Capacity constraints have also shifted some bargaining power away from OEMs towards stronger suppliers.
In addition, selected suppliers are leveraging their manufacturing capabilities and labour-cost advantages to enter the faster-growing areas of aerospace and defence. These opportunities, alongside continued localisation and potential wallet-share gains, have already driven strong share-price performance amongst auto-ancillaries, making valuation discipline increasingly important. We favour suppliers with differentiated products, diversified customer exposure and a credible path to gaining content as localisation deepens.
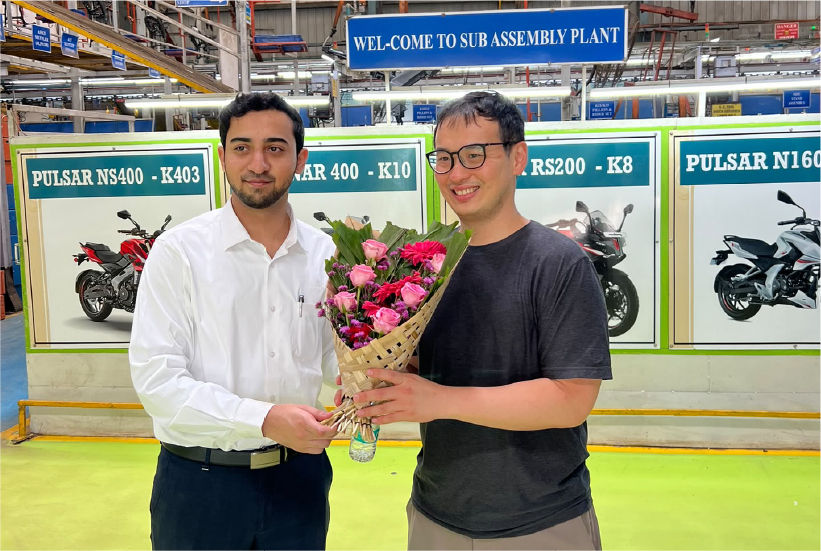
A weekend factory visit; lines were running at full capacity ahead of the festive season
Quick commerce. Convenience is reshaping retail and changing quick commerce from an emergency grocery service into a broader retail channel that offers everything from everyday essentials to electronics, beauty products and books. With delivery speeds now broadly established, competition is shifting towards product availability, range and reliability. Moderating discounts also reflect the increasing value that customers place on convenience. Meanwhile, brands are responding with dedicated inventory, packaging and marketing for the channel.
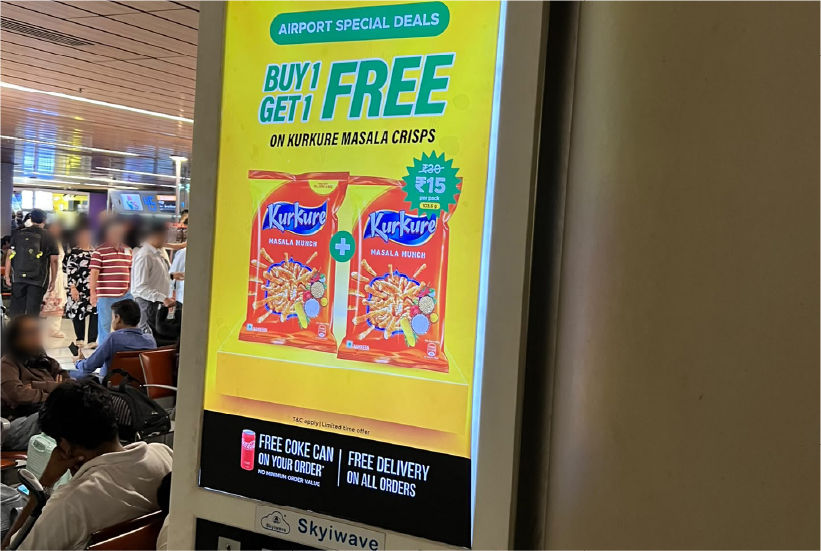
Quick commerce can now deliver right at the airport boarding gate
Hospitals. Hospital stocks have once again been caught up in a debate around pricing regulation following the government's proposal to cap oncology drug prices. This time, the market appears more cautious, possibly because recent regulatory changes have already squeezed earnings in the insurance distribution industry. However, our discussions with hospital operators and industry experts suggest that the proposed price caps are unlikely to have a significant impact. Beyond the pricing debate, we remain optimistic about the consolidation opportunities from large corporate hospital chains. A visit to a recently acquired hospital in Pune helped us to better appreciate how leading operators create post-acquisition value through better doctor recruitment and retention, the addition of higher-value specialties, improved occupancy and a richer case mix. While these operational levers typically take several years to play out, they can drive meaningful margin expansion that is independent of pricing.
Looking through the market weakness
Indian equities may remain volatile with oil price, global yields and foreign outflows dominating market sentiment. Yet the weakness is creating a widening gap between the top-down narrative and the resilience we observed on the ground. We remain selective, but more confident that companies exposed to localisation, rising household incomes and domestic investment can continue to grow through the macro uncertainties. For long-term investors, the Indian equity market offers valuable diversification while its recent underperformance may provide a more attractive entry point to its structural growth opportunities.
Interesting reads
Sources:
1 https://www.autocarpro.in/news/two-wheeler-retail-rises-3308-percent-in-september-2026-fada-135070
Singapore by Eastspring Investments (Singapore) Limited (UEN: 199407631H)
Australia (for wholesale clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore, is exempt from the requirement to hold an Australian financial services licence and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Australian laws
Hong Kong by Eastspring Investments (Hong Kong) Limited and has not been reviewed by the Securities and Futures Commission of Hong Kong.
Indonesia by PT Eastspring Investments Indonesia, an investment manager that is licensed, registered and supervised by the Indonesia Financial Services Authority (OJK).
Malaysia by Eastspring Investments Berhad (200001028634/ 531241-U) and Eastspring Al-Wara’ Investments Berhad (200901017585 / 860682-K) and has not been reviewed by Securities Commission of Malaysia.
Thailand by Eastspring Asset Management (Thailand) Co., Ltd.
United States of America (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is registered with the U.S Securities and Exchange Commission as a registered investment adviser.
European Economic Area (for professional clients only) and Switzerland (for qualified investors only) by Eastspring Investments (Luxembourg) S.A., 26, Boulevard Royal, 2449 Luxembourg, Grand-Duchy of Luxembourg, registered with the Registre de Commerce et des Sociétés (Luxembourg), Register No B 173737.
Chile (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Chilean laws.
The afore-mentioned entities are hereinafter collectively referred to as Eastspring Investments.
The views and opinions contained herein are those of the author, and may not necessarily represent views expressed or reflected in other Eastspring Investments’ communications. This document is solely for information purposes and does not have any regard to the specific investment objective, financial situation and/or particular needs of any specific persons who may receive this document. This document is not intended as an offer, a solicitation of offer or a recommendation, to deal in shares of securities or any financial instruments. It may not be published, circulated, reproduced or distributed without the prior written consent of Eastspring Investments. Reliance upon information in this document is at the sole discretion of the reader. Please carefully study the related information and/or consult your own professional adviser before investing.
Investment involves risks. Past performance of and the predictions, projections, or forecasts on the economy, securities markets or the economic trends of the markets are not necessarily indicative of the future or likely performance of Eastspring Investments or any of the funds managed by Eastspring Investments.
Information herein is believed to be reliable at time of publication. Data from third party sources may have been used in the preparation of this material and Eastspring Investments has not independently verified, validated or audited such data. Where lawfully permitted, Eastspring Investments does not warrant its completeness or accuracy and is not responsible for error of facts or opinion nor shall be liable for damages arising out of any person’s reliance upon this information. Any opinion or estimate contained in this document may subject to change without notice.
Eastspring Investments companies (excluding joint venture companies) are ultimately wholly owned/indirect subsidiaries of Prudential plc of the United Kingdom. Eastspring Investments companies (including joint venture companies) and Prudential plc are not affiliated in any manner with Prudential Financial, Inc., a company whose principal place of business is in the United States of America or with the Prudential Assurance Company Limited, a subsidiary of M&G plc (a company incorporated in the United Kingdom).